News

When can you upgrade or change your medical aid plan, and how to decide

When can you upgrade or change your medical aid plan, and how to decide

Reviewed by Lincoln O’Ehley, General Manager at MedQuote

Published by MedicalAid.co.za | Last updated: 12 October 2026

MedicalAid.co.za is a free comparison service. It is not a medical scheme and does not provide cover.

THE SHORT ANSWER

Review season is when you decide whether to upgrade, downgrade, change scheme or stay. Most schemes open their option-change window from around October and keep it open to the end of December, though some close earlier. The change takes effect on 1 January, unless otherwise specified. You can apply to join a different scheme at any time of year.

That is the short answer. The longer one matters, because schemes publish next year’s changes at different points during the benefit review season, so the gap between having the information and having to decide can be short. This page sets out the dates, what changes, and five checks to do before you make your decision.

When you can change your plan: the annual option-change window

DEFINITION

Option-change window: the period each year when a scheme lets existing members move to a different option on the same scheme. Changing to a different scheme is a separate process and is not limited to this window.

Medical schemes operate under the Medical Schemes Act 131 of 1998 and are regulated by the Council for Medical Schemes. The Act sets no national date for changing options. Each scheme submits its proposed premium increases and benefit changes to the Council, but schemes can decide when to open their option-change window.

If you don’t want to stay on your option, then there is one of two changes you’re able to make:

  • Changing option on your current scheme. During the annual window, or mid-year on a motivated application.
  • Changing to a different scheme. You can apply at any time of year, the acceptance of which is subject to underwriting and waiting periods. Most do it at review season.

The annual cycle is consistent across schemes even though the dates are not:

  1. The scheme submits next year’s contributions and benefits to the Council for review.
  2. The scheme notifies members of what is changing on each option, usually between September and November.
  3. The window opens, and members may move between options or to another scheme.
  4. The window closes. Changes usually take effect on 1 January, though a scheme can defer an increase.

Why the window is shorter than it looks

The window in the table below can run for weeks, but the useful part of it is shorter. Schemes publish next year’s contributions and benefit changes at different points, generally between September and November, so the time you have to compare is often shorter than the window in which you can change.

A scheme cannot ask members to choose until next year’s contributions and benefits have cleared the Council’s annual review. It then has to load the new option, move registrations, and let employers adjust payroll before 1 January.

Two dates are worth asking your scheme for: the closing date of the window, and any earlier deadline for submitting a change so it can be processed before 1 January.

Option-change windows by scheme

Listed alphabetically. The order is not a ranking. These are among the larger open schemes, not a complete list of those in South Africa.

Scheme (alphabetical) Option-change window for 2027 Effective date
Bestmed Medical Scheme 1 Oct – 31 Dec 2026 1 Jan 2027
Bonitas Medical Fund 20 Oct – 30 Nov 2026 1 Jan 2027
Discovery Health Medical Scheme 29 Oct – 30 Nov 2026 1 Jan 2027
Fedhealth Medical Scheme 1 Oct – 30 Nov 2026 1 Jan 2027
KeyHealth Medical Scheme 12 Oct – 15 Dec 2026 1 Jan 2027
Medihelp Medical Scheme 1 Oct – 30 Nov 2026 1 Jan 2027
Medshield Medical Scheme 20 Oct – 15 Dec 2026 1 Jan 2027
Momentum Medical Scheme 20 Oct – 30 Nov 2026 1 Jan 2027

Maintained by MedicalAid.co.za. Dates accurate as of 9 October 2026. Schemes marked as not yet announced will be added as they announce. Dates change annually and schemes sometimes extend a window at short notice. Contribution increases and benefit changes do not always take effect on the same date.

Can you change your plan during the year?

Yes, but acceptance of your application isn’t guaranteed. A mid-year option change needs a motivated application your scheme approves, on grounds set out in its rules. Those rules differ by scheme, including whether a downgrade is treated differently from an upgrade.

Reasons commonly considered by the scheme:

  • Moving to another province where you will need a different network list for designated service providers. For example, if you were on a plan that focused on a coastal network, but you move inland then you need a plan that has a network focused on inland providers.
  • A life-changing event, such as pregnancy, marriage or a new medical diagnosis (e.g., cancer).
  • A change in employment, where you join or leave an employer group with its own options.

Where a scheme discontinues or restructures your option it will tell you and offer a replacement, under the rules it registers with the Council. If you do not respond you are usually moved onto it automatically.

“Members are often moved onto a replacement option without realising it, because the notice reads like administration rather than a decision, so ensure that you understand how your current plan may be impacted for the following benefit year,” says Lincoln O’Ehley, General Manager at MedQuote.

Changing to a different scheme is less restricted. You can apply at any time of year, approval of which is subject to underwriting and waiting periods, covered on MedXpert’s guide to waiting periods and underwriting.

What actually changes at review season

Five things are reviewed annually and your contribution is only one of them.

  1. Your contribution. Increases are announced and are subject to approval by the Council for Medical Schemes.
  2. The benefit structure of your option. Limits, sub-limits, savings allocations, and co-payment rules can all change, so assess whether the new benefits offer sufficient value for money.
  3. Which options exist. Schemes close, merge and restructure options. An example of the latter would be changing an option from a traditional structure to a savings-focused structure.
  4. The provider network. Provider arrangements are renegotiated annually, so your current provider might not be on the list for the next year.
  5. The medicine formulary. The list of medicines covered in full is reviewed annually. If your current medicine isn’t approved, then look at whether a generic will be covered. If neither is covered by the plan, then you will need to cover those costs out-of-pocket.

The decision: five checks to run against your current plan

The big question is whether your plan’s changes will still meet your needs. The first four checks need only your scheme’s information.

Check 1. Has your usage changed since you chose this option?

Pull your last twelve months of claims from your scheme’s app and see where the money went. If day-to-day claims have grown while hospital claims stayed at zero, or the reverse, you might benefit from a different type of plan that has a greater focus on day-to-day benefits.

Check 2. Has your option’s benefit structure changed for the coming year?

Read the benefit change communication, not only the contribution letter. Having a good idea of how your plan has changed will help you understand if your new benefits fit your needs. Was there a reduced sub-limit, or an added co-payment, or a change in Savings allocation? How was my chronic care programme changed and what can I expect from the network list? These are all checks worth making.

Check 3. Are your providers still in network?

Check your GP, specialist, hospital and pharmacy against next year’s network list. If your GP has been removed from the network and you continue to consult with them then you’ll need to shoulder the additional costs.

Check 4. Is your chronic medicine still on the formulary?

If you or a dependant is registered for chronic medication, check each item against the formulary for the option you will be on in January.

Check 5. Would the same contribution buy a different type of plan?

Look at your contribution and compare it against other plans with a similar contribution, be it with your scheme or with another scheme, and look at what benefits that plan has vs what your plan has. Are you able to extract the same value for money on a Savings option vs a Traditional one? The point is not a premium, but the value for money.

Upgrade, downgrade, change scheme or stay

No single answer fits everyone.

What the checks showed What that points to
Your claims exceed your option’s limits, or you pay out of pocket for cover you expected to have Look at whether a different plan type covers what you claim for and use that as a guide to upgrade or move to another option.
You claim well under your limits and your savings allocation carries over unused each year Look at what you pay for and do not use. You might benefit from a lower premium option that has a different benefit structure if your needs will still be met.
Your providers or your medicines are no longer covered as they were Check whether another option, or another scheme, keeps them. If you know that the changing network won’t suit you then use the benefit review window to move to a different plan. If you move midyear to a new province that doesn’t fit into your current network, then you can request an option change outside of the window and your scheme will review the request.
Your claims match your option, your providers are on the network lists, and your medicines are on the formulary If these points hold, staying on your current option is a reasonable outcome. If the new contribution is outside your budget, consider which benefits you could give up by moving to a lower option.

Your review-season checklist

Six steps, in order, before your scheme’s window closes.

  1. Find your scheme’s closing date and ensure your application is submitted well before then.
  2. Work through the five checks above with a specific focus on your claim patterns and your needs.
  3. Add up what you paid out of pocket this year.
  4. Compare against the other options on your scheme at a similar contribution.
  5. Compare across other open schemes at a similar contribution.
  6. Submit your change in writing before the closing date and keep the confirmation.

If you decide to move, and by when

Changing options on your current scheme is the simpler route. Complete the form before the closing date, make a note of your query number and keep an eye on your inbox for your new membership certificate.

If you register chronic medication, you need to ensure that your condition and medicine are authorised for the new year. This includes ensuring that your network pharmacy has the most recent script. If your network pharmacy needs to deliver your medication each month then confirm the delivery address and if any co-payments will be applicable for the new year.

Changing scheme involves underwriting and follows a unique process, so start early if it’s something you want to do. You can compare open medical schemes side by side on MedicalAid.co.za, free of charge, and request a call back.

Frequently asked questions

Can I change my medical aid during the year, or only in January?

Changing option outside the annual window needs a motivated application the scheme approves, on grounds set out in its rules, such as a life-changing event like having a baby or moving to a different province. Changing scheme isn’t restricted: you can apply at any time of year, but admissions will be subject to underwriting and waiting periods.

When does medical aid review season start in South Africa?

Schemes usually publish contribution and benefit changes between September and November, and option-change windows generally run from around October to the end of December, though some schemes close earlier, for changes effective 1 January. Exact dates differ by scheme, but the Medical Schemes Act requires that there is a period of at least 30 days before any changes are put in place.

If I change my option, do I have to serve waiting periods again?

If you move options within the same scheme, your waiting periods will not start over. You might carry over your waiting period if it hasn’t ended by the time you move options, but you won’t serve the same waiting period again. Waiting periods and underwriting are complex and are governed by the Act and the scheme’s rules. See MedXpert’s guide to waiting periods and underwriting.

My contribution is going up. What should I check if I want to stay on the same plan?

Check whether the increase comes with a change in benefit structure, or whether another option allocates the same money differently and in a way that could meet your needs better. Confirm that your service providers and medicines are still covered by your option’s network and formularies. Look for co-payments and consider how it will affect your pocket, as well as if gap cover is something worth taking out.
Medical aid tax credit in South Africa: What families need to know

Did you know SARS reduces your tax bill every month you’re on medical aid? Most South African families don’t, and the ones who do often aren’t claiming it correctly. It’s called the medical aid tax credit, and for a family of four, it’s worth R14,640 a year.

It applies to the principal member, their spouse, and all registered dependants. Your income doesn’t affect your eligibility. And it’s separate from the Additional Medical Expenses Tax Credit, which covers qualifying out-of-pocket costs your scheme doesn’t pay for.

Here’s how it works for the 2026 tax season.

What’s the medical aid tax credit?

Each month you’re on a registered medical scheme, SARS knocks a fixed amount off your tax bill. That’s the Medical Tax Credit, Section 6A of the Income Tax Act, for the record. It’s not a deduction. Deductions reduce your taxable income before the number is worked out. This reduces the number itself. For most families, that difference translates into real money. That makes it more valuable, rand for rand, particularly for families in middle-income brackets.

The credit was put in place to bring down the effective cost of medical aid membership.

 How much is the credit worth in 2026?

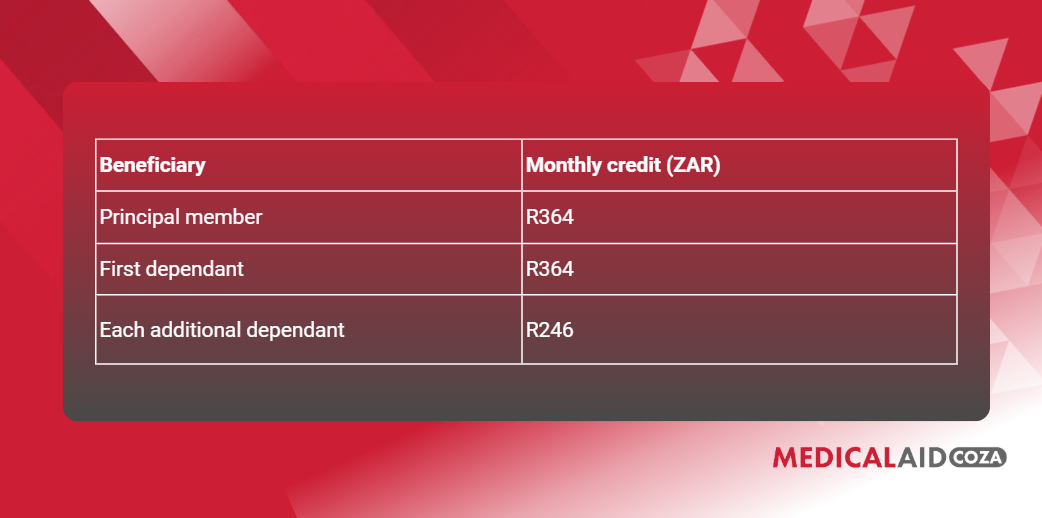
SARS sets the medical aid tax credit 2026 amounts annually. For the 2026 tax year (1 March 2025 to 28 February 2026), the applicable amounts are:

A family of four (two adults, two children) receives a combined monthly credit of R1,220, or R14,640 over the full tax year.

Always verify the latest figures directly with SARS or your tax practitioner, as these amounts are subject to annual revision.

How does it reduce your tax bill?

The credit is applied after your income tax liability has been calculated. It is subtracted directly from what you owe SARS, not from your income before the calculation.

Worked example for a family of four:

Calculated tax liability R42,000
Annual MTC (family of four) R14,640
Tax payable after credit R27,360

R14,640 back in your pocket. For a household carrying medical aid contributions on top of school fees and groceries, that’s not a small number.

How do you claim the medical aid tax credit?

For most employed South Africans, the process is largely automatic. Here is how to claim medical aid tax credit correctly:

  1. Your employer deducts your medical aid contributions from your salary each month.
  2. The MTC is factored into your PAYE calculation by your employer’s payroll system, reducing your monthly tax deduction.
  3. At tax filing time, you declare your contributions on your ITR12 return.
  4. SARS calculates and applies the credit automatically based on the number of registered beneficiaries on your plan.
  5. If you are self-employed, you claim the credit manually when submitting your annual return.

When filing your ITR12 medical aid credit section, have your annual contribution certificate ready. Your scheme issues this after the tax year ends. It confirms the total contributions paid and the number of registered dependants.

Does your plan affect what you can claim?

The MTC amount is fixed regardless of which medical aid plan you are on. However, the plan you choose does affect your total out-of-pocket healthcare costs, and that matters when it comes to a second credit.

The Additional Medical Expenses Tax Credit (AMTC) allows qualifying taxpayers to claim a portion of medical expenses not covered by their scheme. This applies mainly to South Africans aged 65 and over, or those with a disability, whose qualifying out-of-pocket expenses exceed a set threshold.

For families under 65 without a disability, the MTC is where the focus sits. A plan with a low monthly contribution sounds good until you add up what you’re spending at the doctor, pharmacy, and hospital. Are you sure your current plan is giving your household value? You can read more in our guide, Does your current medical aid still fit your needs?, or compare options directly on MedicalAid.co.za.

View medical aid options on MedicalAid.co.za to see how plans differ based on your household size and budget.

Frequently asked questions

Is the medical aid tax credit the same as a tax deduction?

No. A deduction reduces your taxable income before your tax is worked out. A tax credit reduces your actual tax liability after the calculation. Credits are generally more valuable because they reduce your bill rand for rand, regardless of your tax bracket.

What’s the difference between the MTC and the SARS medical aid rebate?

They’re the same thing. The SARS medical aid rebate is the name that was used before the system was formalised as the Medical Tax Credit under Section 6A. Both refer to the fixed monthly credit applied to your tax liability for contributions to a registered scheme.

What if my employer pays part of my medical aid?

The MTC applies to the full contribution, regardless of who pays it. However, the portion paid by your employer is treated as a fringe benefit for tax purposes. Speak to a tax practitioner if you are unsure how this affects your overall return.

Can I claim for dependants who are no longer on my plan?

No. The credit only applies to registered dependants for the months they were active on your plan. If a dependant was removed mid-year, the credit applies only for the period they were covered.

Find a plan that works harder for your family

The medical aid tax credit exists to reduce what your family pays. But it works alongside your plan, and if your plan isn’t the right fit for your household’s needs and budget, you’re not getting the full picture. When last did you compare your options? Families at different life stages often find the numbers look different when they sit down and check. If someone in your household is newer to medical aid, our guide on what young professionals should compare before joining is worth a read, too.

Compare medical aid options on MedicalAid.co.za and see which plans give your household the best combination of cover and value.

Your mid-year medical aid check-in: 5 things to review before your benefits run out

It’s June. If you’re like most South Africans on medical aid, you haven’t opened your scheme’s app since your first GP claim in February. Life moved on. Work got busy. The app stayed buried in a folder on your phone.

We are here to gently remind you that the halfway point of the year is actually the most useful time to check in on your medical aid, not because something is wrong, but because you still have time to fix it if it is. By November, when schemes open their annual review window, half your benefits may already be gone, and your preventive screenings still unused.

This isn’t a “should you switch” article. It’s a five-point check-in that takes less than an hour and could save you from some expensive surprises in the second half of 2026.

1. Check your medical savings account balance before it’s gone

Most medical aid plans place part of your monthly contribution into a Medical Savings Account, known as an MSA. This pool of money pays for day-to-day healthcare expenses such as GP visits, dentistry, optometry, and acute medication.

The MSA is separate from your risk benefits, which cover things like hospitalisation and certain chronic conditions. This distinction matters because your MSA can run dry, and when it does, you pay out of pocket for every GP visit and prescription until January.

If you’ve had a couple of illnesses, dental work, or a family member that visits the doctor regularly, there’s a real chance your MSA is already running low by June.

What should you do?

Log into your scheme’s app or member portal and look for your “savings balance” or “day-to-day benefits remaining.” Most major schemes display this clearly on the dashboard. If yours doesn’t, call the member helpline and ask for your current savings balance and year-to-date claims.

Pay attention to what remains halfway through the year. If your MSA balance sits below 30% or 40% by June, you’re moving toward depletion before December. Knowing this now changes how you plan the rest of the year.

2. See how much of your annual benefits you’ve actually used

Beyond your MSA, most plans include annual limits for specific benefit categories. These work differently from your savings: they don’t run dry in the same way, but once you’ve hit the limit for the year, claims in that category stop paying out.
The categories to check:

  • GP consultations – some plans limit the number of visits or the total rand value covered per year for GP consultations.
  • Acute medication – this usually comes from savings, but some plans apply separate limits.
  • Dental – most plans have an annual dental benefit, separate from savings.
  • Optical – typically a biannual benefit with a fixed amount for frames, lenses, and eye tests.
  • Radiology and pathology – X-rays, blood tests, and scans often draw from both savings and risk benefits depending on the plan.

Pull up your year-to-date claims statement through your member portal and run through each category. The question isn’t whether you’ve used a lot, it’s whether you’re pacing correctly for the rest of the year.

If you’ve used 70% of your dental benefits by June, you know to space out any non-urgent dental work. If you’ve barely touched your optical benefit and need new glasses, now is the time, not in November when everyone else has the same idea.

While reviewing your statement, look for rejected claims. Many people ignore them after the first rejection notice arrives. Yet some claims fail because of missing codes, missing documents, or submission errors. A rejected claim from April still deserves attention in June.

3. Book those preventive screenings before Q4 gets busy

This is the one most people forget, and it’s the most straightforward item on this list.

Most medical aid plans in South Africa cover a range of annual preventive screenings at no cost to you from the risk pool. That means these screenings don’t touch your MSA. They’re a genuine benefit you’re entitled to, and most members either don’t know about them or keep meaning to book them.

Depending on your scheme and plan, covered screenings typically include:

  • Blood glucose (diabetes screening)
  • Cholesterol and blood pressure checks
  • Pap smears (annual for women)
  • Mammograms (frequency varies by age)
  • Prostate-specific antigen (PSA) tests for men from a certain age
  • BMI and general wellness assessments

The reason to book them now is all about availability. GP practices and wellness clinics are genuinely busier in Q4. They are busier because people are rushing to use benefits before year-end, or due to seasonal illness, and appointment slots are becoming scarce. Booking in June or July means you get the time slot you want.

Check your scheme’s benefit schedule or call your GP to confirm which screenings are covered under your specific plan. Then book. It takes ten minutes and you won’t have to think about it again.

4. Make sure your dependants are still correctly registered

Dependant details seem like admin, and they are, until you need to claim on behalf of someone whose information is out of date.

The common situations that cause problems:

  • A child turning 21 – most schemes remove child dependants at 21 unless they’re registered as full-time students or meet specific criteria. If your child turned 21 this year and is still studying, you may need to submit a student affidavit to keep their cover active.
  • A new baby – newborn registration creates another risk. Most schemes require babies to be added within a specific period after birth. Miss the deadline and waiting periods enter the conversation.
  • Marriage or divorce – adding a spouse or removing an ex-spouse requires formal scheme notification, usually with supporting documentation.
  • A dependant who passed away – removing a deceased dependant matters for premium calculations going forward.

When a claim is submitted for an incorrectly registered dependant, the scheme can reject it. You can appeal, but that takes time. The fix is simpler before the claim happens.

Log into your member portal, check the list of registered dependants, and confirm the information is current. If anything needs updating, contact your scheme’s member services directly.

5. Ask yourself: does this plan still fit your life?

This isn’t the same question as “should I switch medical aids?” It’s a more honest question about whether the plan you chose in January, or two years ago, still matches what your family needs.

Three questions worth sitting with

Is your MSA running out faster than expected? If you’re consistently depleted by mid-year, your plan’s savings allocation may be too low for your household’s actual usage. A plan with a larger savings component might serve you better.

Are you paying for benefits you’re not using? If you’re on a comprehensive plan and your family hasn’t had a single in-hospital event in years, you might be over-insured for what you’re actually using.

Has your family structure changed? A new baby, an ageing parent added as a dependant, or a child leaving the plan, all these changes what your plan needs to do.

This is where MedicalAid.co.za’s comparison tool earns its place. Enter your age, income, and family size, and compare plans side-by-side without committing to anything. It’s free, takes a few minutes, and gives you a clear picture of what else is available before the formal annual review period opens later in the year.

Doing this in June means you have time to think it through properly, rather than making a rushed call in November.

Does your current medical aid still fit your needs?

If you have caught yourself asking, “does my medical aid cover my needs?”, you’re not alone. Many South Africans stay on the same medical aid plan for years, even as their life, health needs, and monthly income and expenses change.

With medical aid costs escalating, it could be worth investigating whether your cover still fits your needs. For all you know, you could be saving thousands of rands in the long run.

That’s why it’s important to have a self-check system to help you spot when your current option may no longer be the right fit.

If a few of the signs below feel familiar, you can view options on Medicalaid.co.za to compare monthly costs and benefits based on your household details, before opting for “the cheapest” one.

Why “fit” changes over time

The medical aid plan that worked when you started your first job might not work as well now. Life doesn’t stand still, and neither should your medical cover. A new marriage, a growing family, a salary increase, or a health diagnosis can all shift what you need from your plan.

It also helps to remember that medical scheme benefits and rules differ by scheme and by option. Even when two options sound similar, they may handle day to day limits, hospital networks, and co-payments differently.

The goal is not simply “the cheapest”. It’s the best match between what you pay in monthly contributions and the benefits you’re most likely to use.

7 signs your current option may not match your needs

1.     Your monthly contribution has become difficult to manage

If contributions are rising faster than your income, it may be time to reassess what you genuinely use versus what you’re paying for.

 2.     You’re paying out of pocket more than expected

Many out-of-hospital benefits have limits and rules. Depending on the option, co-payments can apply, and some services may be subject to benefit caps.

3.     Your family structure changed

Getting married, adding dependents, or planning for a baby can all change what kind of medical aid suits you best. So can your children’s needs, like dental check-ups or getting spectacles.

4.     You are using the hospital more or planning a procedure

If hospital admissions, specialist consultations, or planned procedures are becoming more likely, review:

  • hospital benefits,
  • pre-authorisation rules,
  • network requirements,
  • and what can trigger co-payments.

5.     You have a new diagnosis or ongoing medicine needs

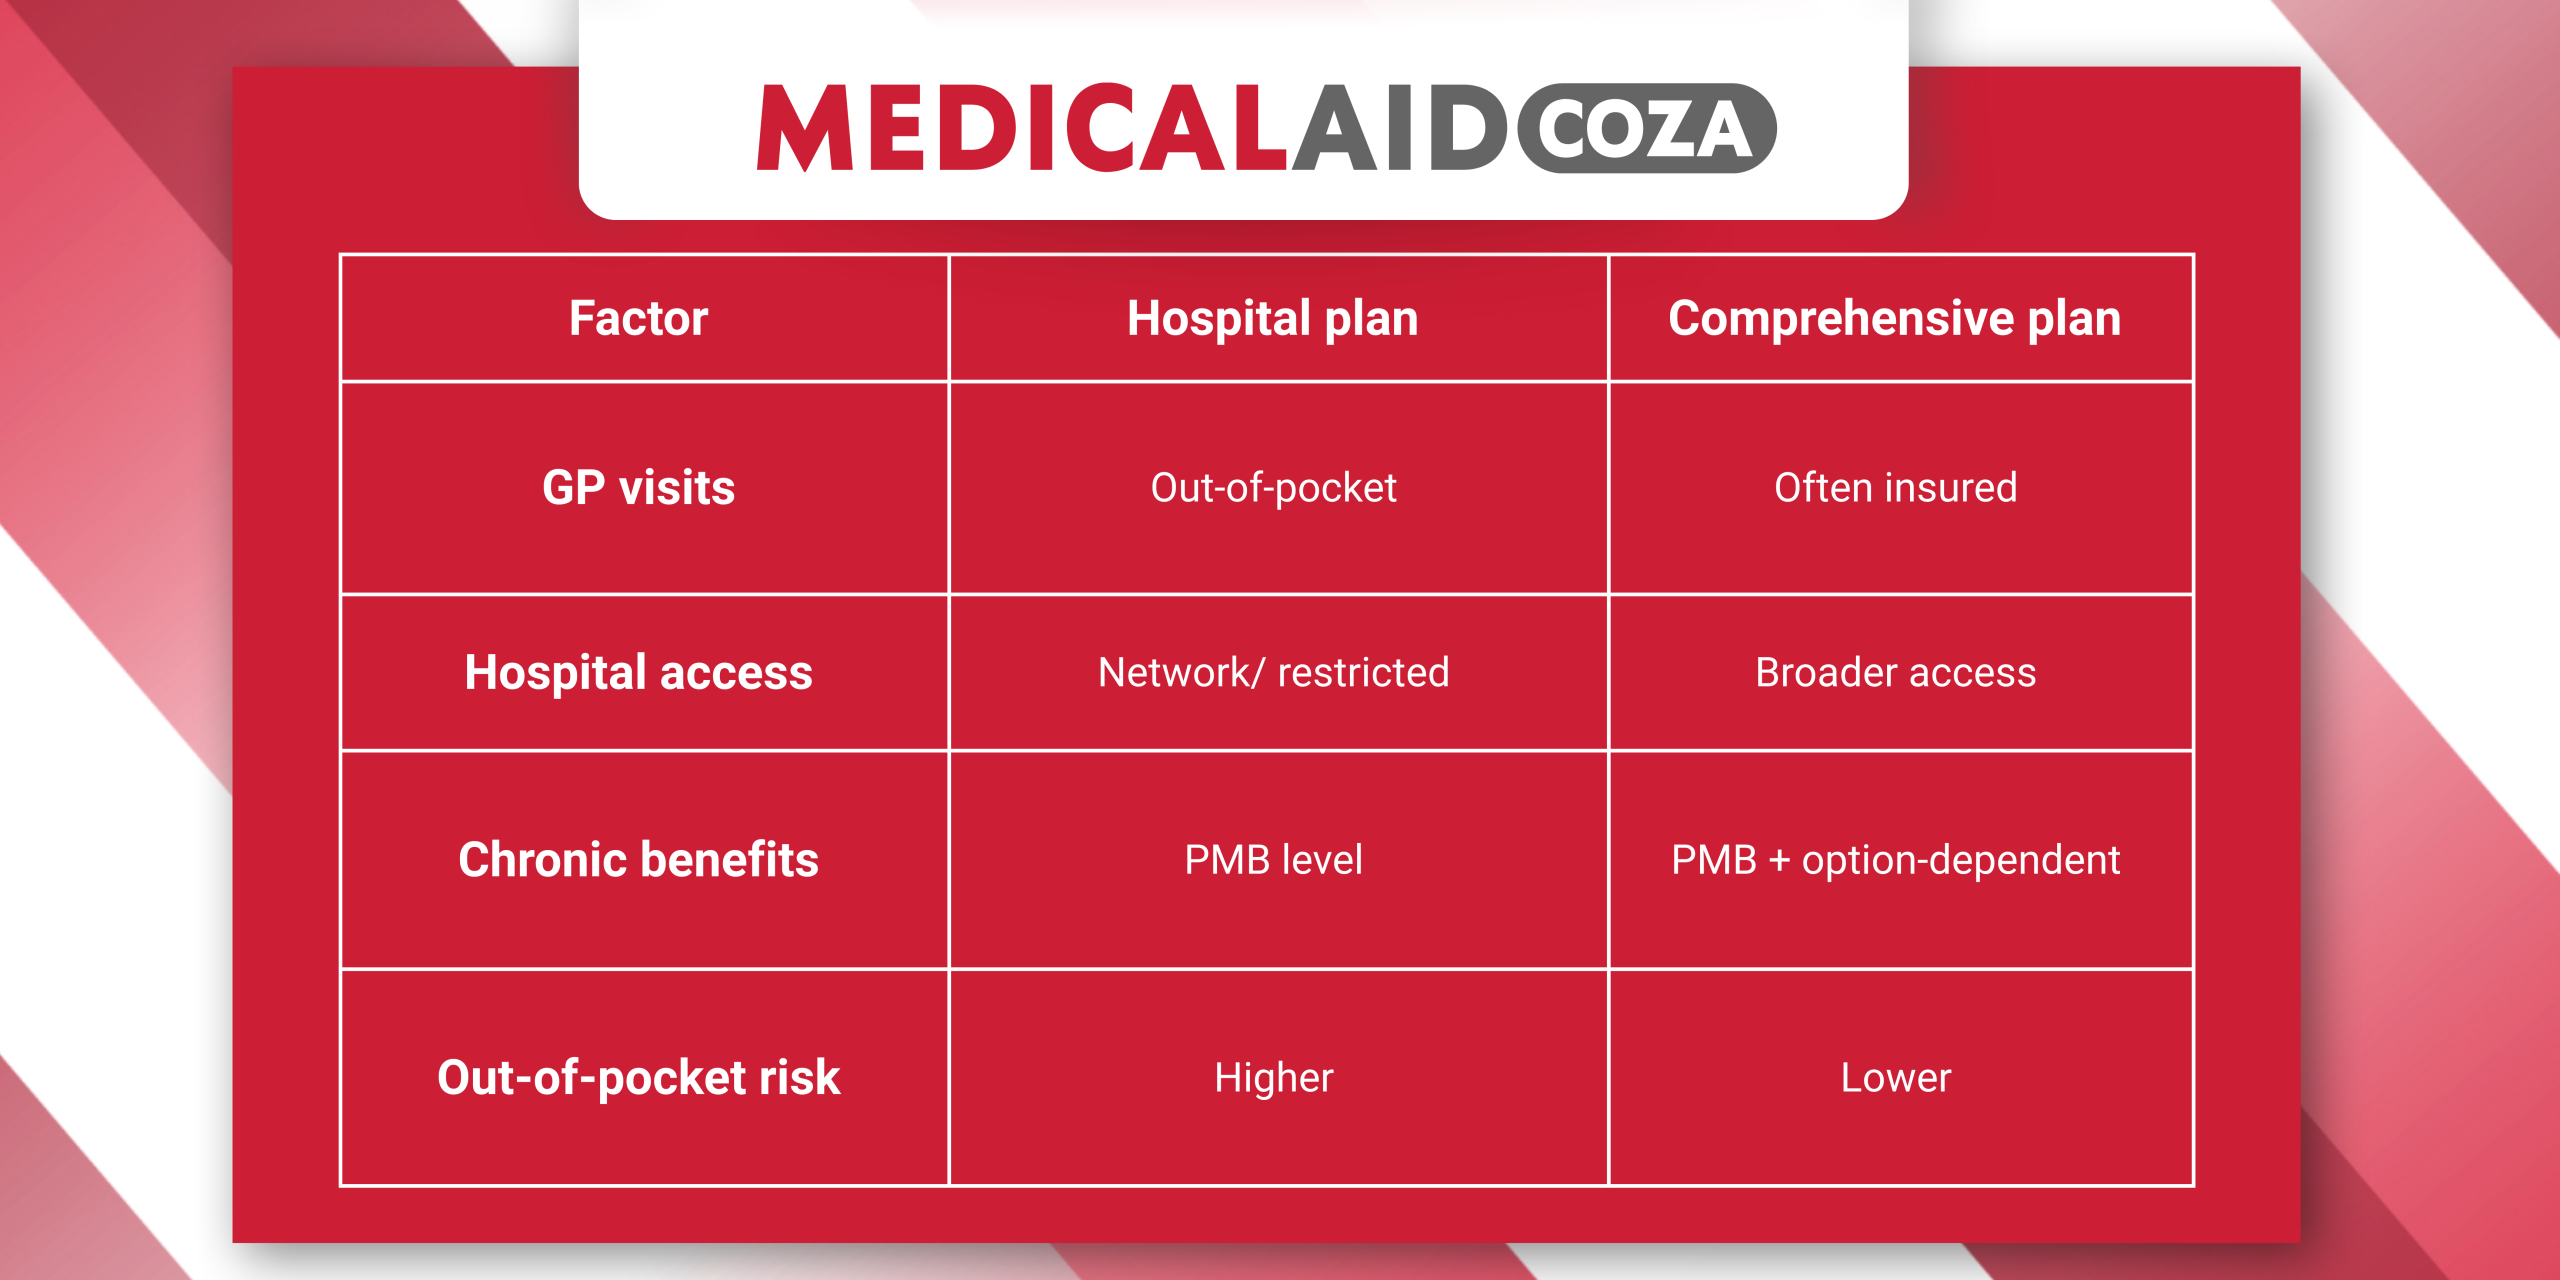
Prescribed Minimum Benefits (PMBs) are a regulated set of benefits that cover specific conditions, no matter which medical aid plan you choose, but schemes may apply processes and treatment protocols.

6.     Your option’s network rules do not match where you get care.

Some options are built around a network or Designated Service Provider (DSP) arrangement. Using providers outside that arrangement can affect what is paid.

7.     You have not reviewed your benefits in 12 months

An annual review helps you avoid “set and forget”. Your needs, budget, and the option’s rules may have changed.

If two or more signs apply, it may be time to view options and compare monthly costs and benefits based on your household needs.

What to review before you switch or upgrade

Benefit category match

Use a simple “what do I use?” lens:

  • Day-to-day benefits: General Practitioner (GP) visits, basic dentistry, basic optometry, acute medicine, and related limits.
  • Hospital benefits: admission rules, authorisation requirements, and network arrangements.
  • Chronic medicine arrangements: how ongoing medicine is managed, and what processes apply.
  • Family needs: dependants, maternity related benefits (if relevant), and children’s routine care.

A quick way to ground this is to look back at the last three to six months of claims and receipts, then compare that against the option’s stated benefits and rules.

Example scenario (young professional)

You start your first job and mostly need GP visits and the odd dental check-up. A year later, you begin seeing a specialist and your out-of-pocket costs increase. That’s a clear sign it’s time to review your plan and check if your day-to-day benefits and specialist cover still meet your needs.

Example scenario (family)

You add a spouse and child, and suddenly there are more dental visits, eye tests, and trips to the pharmacy. When your family grows, it’s a good time to review your cover by checking dependant rules, day-to-day limits, and hospital network requirements to make sure your plan still fits.

Rules that can affect access to benefits

Two rule areas often surprise people:

  • Waiting periods: these can apply for new members depending on circumstances, and full disclosure matters.
  • Late joiner penalties: these may apply in certain cases under the Regulation 13 of the Medical Scheme Act. (often linked to joining after the age of 35 and not belonging to a scheme for a long period).

Because these topics can be technical, keep it high level at first and confirm details in the official scheme rules before acting.

Before you switch, compare monthly costs and benefits side by side so you can see how options differ for your household. View options on Medicalaid.co.za.

The simplest way to sanity-check your fit: compare your options

If you’re unsure what to do next, start with a clean comparison. Medicalaid.co.za is a decision support tool that lets you enter your age, income, and family structure to see real monthly costs and plain language benefit explanations.

Comparison supports informed decision making. It doesn’t guarantee savings, and you should always confirm final details in official scheme rules.

Ready for a clearer view? View options on Medicalaid.co.za to compare monthly costs and benefits based on your household needs.

5 Smart Medical Aid Tasks to Start the Year Right

5 Smart medical aid tasks to do in January

Still recovering from festive spending? Your healthcare costs shouldn’t be the next surprise. For South Africans on medical aid, January is the most valuable time to lock in smart healthcare moves.

Think of it like a reset button for your healthcare. Get ahead now, and you’ll avoid unnecessary payments, claim rejections, and late-year panic.

Here are five simple but powerful tasks you can do this month to make sure your medical aid works for you.

1) Set up your preventive screenings early

Most medical aid schemes in South Africa cover essential preventive health screenings at no cost to you. These include:

  • Pap smears
  • Mammograms
  • Prostate exams
  • Cholesterol checks
  • Glucose tests

These medical aid benefits are often paid from your risk portion, not your savings, meaning they don’t reduce your available day-to-day funds.

January is the best time to book them. Not only are healthcare providers typically less busy, but it’s also easier to secure appointments that fit your schedule. Booking early also reduces the chance of forgetting about them altogether.

Some schemes, like Discovery’s Personal Health Fund,  reward members for staying proactive about their health. When you complete your annual health checks, you can unlock funds in your Personal Health Fund to use for everyday medical needs – including physio, mental health support or other out-of-hospital expenses. Many other medical schemes offer similar incentives for preventive care, encouraging members to act early rather than waiting until something goes wrong.

2) Check your savings and day-to-day medical aid benefits upfront

One of the easiest ways to lose money on medical aid is to misunderstand how your plan splits benefit between risk and savings.

Start by logging into your medical aid app or online portal. A healthcare broker can also help you with your needs analysis.

Take note of your:

  • Available medical savings balance
  • Annual day-to-day benefit limits
  • What services are covered under “risk” (typically includes screenings, chronic medication, immunisations)

For example, children’s vaccinations and dental checkups are usually paid from risk. But if you don’t claim them correctly or if the provider isn’t coded correctly, you could unintentionally use up your savings early in the year.

A few minutes now can help you avoid using your entire savings allocation before March.

3) Download your scheme’s app and activate digital authorisations

Medical aid apps are more than just balance checkers. They help you manage your medical aid benefits in real time.

If you haven’t already, download your scheme’s app and explore features like:

  • Digital pre-authorisations for hospital visits or specialist consultations
  • Claim submissions via photos or digital uploads
  • Provider search tools to find network-approved doctors or hospitals
  • Real-time benefit tracking

This isn’t just about convenience. If you can submit claims and authorisations quickly, you reduce the risk of delays or admin errors that lead to out-of-pocket payments. Plus, getting to grips with the app now means you’re ready when a real medical need arises later.

4) Make sure dependents still meet eligibility rules

Many members get caught out by dependent eligibility changes, especially after December, when children turn 21 or return to university.

Most medical aid schemes require updated documents for adult dependents. If your child is over 21 but still studying, you’ll likely need to submit a proof of registration or similar documentation. If that’s not done, they may be removed or reclassified as adult members, which often means:

  • Higher monthly premiums
  • Claims being rejected unexpectedly

Also, check whether new dependents (like a baby born in December) have been added and approved. Don’t assume the paperwork is automatic.

5) Review your DSPs for medication and planned procedures

Designated Service Providers (DSPs) are a critical part of managing your medical aid costs. Every scheme has a network of preferred:

  • Pharmacies
  • Hospitals
  • Medical specialists
  • Dentists
  • General Practitioners (GP)

If you use a provider outside your scheme’s Designated Service Provider (DSP) network, especially for chronic medication or planned procedures, you could face steep co-payments. Gap cover can help you with these types of co-payments

In January, go through your scheme’s updated 2026 DSP list. Make sure your:

  • GP is still in-network
  • Pharmacy is listed for chronic meds
  • Hospital choice for planned procedures is covered

If you need to switch providers, better to do it now before you need treatment.

For example, getting chronic medication from a pharmacy not on your network, can lead to an on average 30% co-payment (be sure to confirm with your broker and your scheme what sort of co-payment applies to your specific option. That’s a costly mistake that’s easy to avoid with a quick check.

Final Tip: One hour now can save you thousands later

Medical aid in South Africa is complex, but it’s not beyond your control. Spending just an hour in January reviewing your medical aid benefits, checking balances, and updating documents can save you thousands in avoidable expenses later in the year.

Think of it like setting up debit orders or doing your tax prep. It’s admin that pays off.

Already locked into your 2026 plan? No problem. You can still use MedicalAid.co.za to compare medical aid benefits, understand how your plan stacks up, and prepare better questions for your broker or scheme. It’s a smart way to stay informed, so your medical aid works for you all year.

What to do if you need emergency care over the festive season

Each year, medical schemes review their benefits and contributions. These updates shape how much members pay, and what they receive in return, so taking a moment to understand what’s changing in 2026 can help you make smarter health cover decisions.

The festive season is known as the ‘period of celebration’ that takes place during December and some of January. For many South Africans it’s also the time to slow things down and spend quality time with family and friends, while enjoying a lekker braai.

Although there are much laughter and joy, it’s also a period where the rate of medical emergencies and accidents increase. Many of us don’t know what to do or who to call if an emergency arises. This blog provides you with important steps you can take if an emergency comes your way.

Common emergencies

Hospitals see more of these during December and January:

  • Drowning
  • Road accidents
  • Holiday decorating injuries
  • Food poisoning
  • Kitchen-related injuries
  • Slips and falls
  • Heatstroke

Being prepared matters. Acting correctly matters more.

Step 1: Stay calm and assess

Panic worsens emergencies, so it’s important to breathe. Check for danger. Do not move someone injured unless they are in immediate danger. Rather call emergency services for help. If you are bitten by a snake, try to take a photo of the snake so emergency services can identify if it is venomous and how to proceed.

Step 2: Call the right number

South Africa has multiple emergency lines:

  • 112 from any cell phone connects to all services
  • 10177 is the national ambulance number
  • Netcare 911: 082 911 (Private)
  • ER24: 084 124 (Private)

Private services work with most medical aids. Check your policy schedule to see what ambulance you can use.  Emergency services can guide you, dispatch ambulances, and manage hospital transfers.

Step 3: Pre-Authorisation

In the event of an emergency (ER Visit) the hospital will contact your medical aid for pre-authorisation. The medical aid will then send authorisation straight to the hospital. Remember you will also need to get pre-authorisation if you are admitted into hospital.

Quick tip: Ask if your medical aid has given authorisation for procedures before entering the Operating room, if not how much are they willing to pay. That is where gap cover will step in.

Step 4: Know what counts as a medical emergency

Emergencies include sudden life-threatening conditions that will cause loss of life, serious impairment of bodily function, serious and lasting damage to organs, limbs, or other body parts. These are known as Emergency Prescribed Minimum Benefit’s (PMBs).

Examples:

  • Uncontrolled bleeding
  • Breathing difficulties
  • Fit or epileptic seizure
  • Broken arms
  • Heart attack
  • A stroke

If your case does not meet these criteria, it may not qualify. Ask your provider for clarity.

Step 5: Go to a network hospital

Medical aids cover specific hospitals. Non-network hospitals may result in co-payments or full charges. In the event of an emergency and there is no network hospital within 40km then any hospital will be accepted.

Here are some tips on accessing your network:

  • Save your network hospitals on your phone
  • Check for hospitals near your holiday destination that are in your network
  • Be prepared to tell paramedics your scheme and plan type

Step 6: Keep your details ready

Time is critical. Keep these on hand:

  • Membership card or digital copy.
  • Plan type and number
  • Emergency contact
  • List of chronic conditions and current medication
  • ID copy

Store the details on your phone through your health ID and carry a hard copy in your car or bag.

Step 7: If you travel abroad

Most South African medical aids have limited cover international emergencies.

  • Ask your scheme about travel benefits and how much the maximum amount is
  • Consider travel insurance that covers medical emergencies

A small premium can prevent large bills.

Be prepared

The festive season should not leave you with debt or risk. Not all plans cover transport to hospitals, nor do they offer cover for all hospitals. It’s a good time to take a closer look at your benefits and potentially compare different medical aids in South Africa with MedicalAid.co.za. Ensure your plan covers emergencies, travel, and network hospitals.

Emergencies can happen at any time. During the festive season, services are stretched. Being informed is your protection. Save numbers. Know your cover. Know your nearest hospitals. Have your details ready. Help is only a call away. Will you take steps now to secure care for yourself and your family?


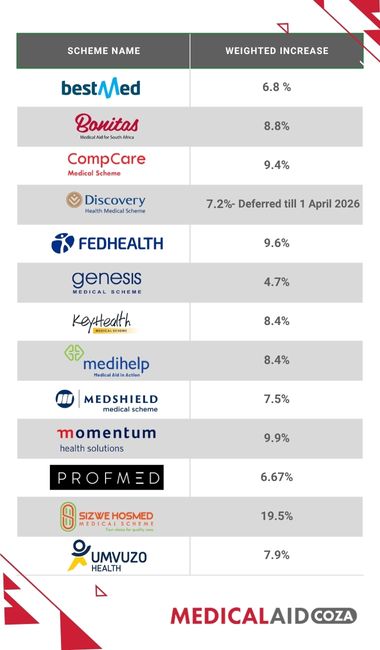
2026 Medical scheme benefit and premium update hub

Each year, medical schemes review their benefits and contributions. These updates shape how much members pay, and what they receive in return, so taking a moment to understand what’s changing in 2026 can help you make smarter health cover decisions.

While increases still need regulatory approval, here’s a snapshot of confirmed updates and new benefits from South Africa’s leading medical schemes.

Bestmed

Bestmed has introduced an average benefit increase of 4.6% across all plans, along with several meaningful enhancements:

  • Preventative care: Faecal occult colon cancer screening is now available every 24 months for members over 40.
  • Surgical cover: Adenoidectomy for both adults and children has been added to the Rhythm 1 option, combined with tonsillectomy benefits.
  • Hearing devices: Cochlear implant and BAHA limits have been raised, up to R350,000 on Pace 4.
  • Breast reduction: Pace 3 and 4 now include a medically necessary breast reduction benefit, capped at R100,000.
  • Take-home medicine: Allowances for chronic and retail pharmacy take-home medication have been increased by at least 175%, now ranging from R450–R700.
  • Contraceptives: Female contraceptive benefits have been split into two clear limits: oral contraceptives (R2,092–R2,801) and IUDs (R3,295–R4,225).

Discovery Health

Discovery’s contribution increases will only apply from 1 April 2026, giving members a few extra months at current rates.

The Smart Saver range, launching 1 January 2026, brings a new combination of value and flexibility, including:

  • Up to 200% hospital cover on the Smart network.
  • A built-in Medical Savings Account.
  • A Personal Health Fund.
  • Unlimited Smart GP visits.
  • Dental, optical, and over-the-counter benefits.

Bonitas

Bonitas is focusing on younger members with its new BonCore plan, designed for individuals and couples aged 22–35. Benefits include:

  • Unlimited network hospital cover.
  • Unlimited virtual GP visits and 3 in-person consultations.
  • Cover for 28 chronic conditions.
  • A R1,000 Benefit Booster.
  • Preventative screenings.

The Primary Select plan has evolved into BonPrime, a savings plan with 16% allocated to savings, giving members more control over everyday costs.

Medihelp

Medihelp has two refreshed options stand out for 2026:

  • MedVital: Improved overall value across key benefits.
  • MedReach (previously MedElect): Now tailored for professionals seeking convenience and quality. Includes unlimited hospital cover, day-to-day benefits, and extended radiology, dental, and eye care coverage. The MedElect Student option has been discontinued.

Medshield

Medshield has a strong focus on screening and chronic care improvements this year:

  • AI Optical Diabetic Screening across all options except MediPhila and MediCurve.
  • Reduced chronic medicine co-payments on most plans.
  • Annual mammograms for women 30+ (previously every two years).
  • Dis-Chem has been added as a Designated Service Provider (DSP) for chronic medication.

Momentum Health

Momentum has introduced several preventive and accessibility upgrades:

  • FIT (Faecal Immunochemical Test): Now available annually for members aged 45–80 on all options except Ingwe.
  • Ingwe income brackets increased by 4.5% to make coverage more accessible.
  • Student/child principal rate: R645 per month.
  • Maternity benefit: Online antenatal and postnatal classes now hosted by ParentSense.
  • Dental cover: Preventative benefit raised to R500 per beneficiary.
  • Average co-payment increases of 4%.

Fedhealth

Fedhealth continues to expand coverage for women’s and mental health, as well as preventative care for seniors:

  • FlexiFED 1: Expanded maternity benefits, including more scans, consultations, and antenatal classes.
  • Mental health: Depression medication now covered even on entry-level plans.
  • Emergency contraception is now covered across all options.
  • Senior care: Pneumococcal vaccine added for members 65+.
  • Oncology: 25% higher brachytherapy limits on FlexiFED 4.
  • Day-to-Day Plus (D2D+): Rewards members who complete a health risk assessment and join Sanlam Health Rewards, unlocking up to R4,500 for additional day-to-day cover.

Compare your cover for 2026

Our updated comparison tool on MedicalAid.co.za now reflects 2026 benefits and contributions across all major schemes. It’s designed to help you see what’s changing, and decide whether your current plan still meets your needs.

Start the new year with confidence. Compare your cover and see exactly what you’ll be getting in 2026.